
Roof Insurance Claims in Arlington, Fort Worth, and Northeast Tarrant County
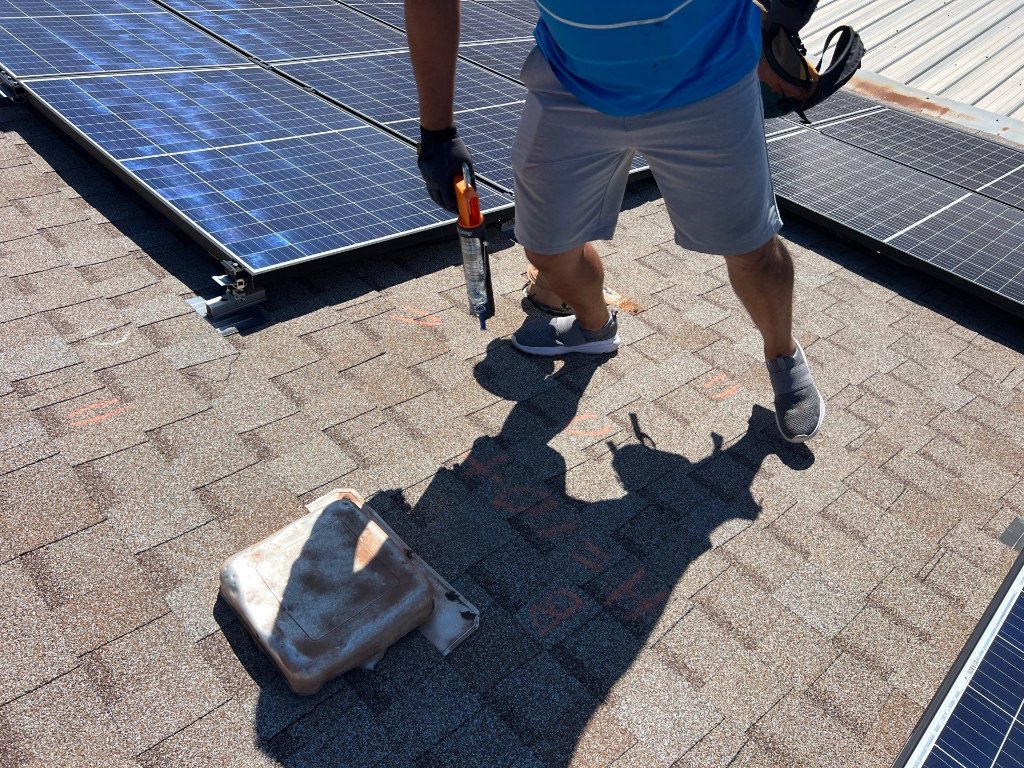 An Arlington, TX roof in the claims process ? documented and scoped while the homeowner’s hail claim works through insurance. (Image from the brexteriors.com gallery.)
Table of Contents
- What Homeowner’s Insurance Covers After Hail in Arlington
- Understanding Your Texas Wind/Hail Deductible
- ACV vs. RCV: How You Actually Get Paid
- The Texas Filing Window and Why Timing Matters
- How to File an Arlington Roof Claim, Step by Step
- Why Claims Get Denied or Underpaid
- Why Arlington Homeowners Work With Becker on Claims
- Frequently Asked Questions
If you’re an Arlington homeowner staring at a hail-battered roof after a North Texas storm, the first question is usually the same: what will my insurance actually pay for? It’s a fair question, and the answer has a lot of moving parts ? coverage type, your deductible, ACV versus RCV, and the Texas filing timeline. Arlington sits right in the DFW hail alley, and recent seasons have been brutal: the April 25?26, 2026 severe complex dropped hail up to three inches near Arlington and drove 90 mph gusts through the western Metroplex (WFAA). This guide breaks down what’s covered, what isn’t, and how to file the right way.
For a hands-on look at what to do the moment hail hits, pair this with our Arlington hail damage roof repair guide. If you need help now, call Becker at 817-898-7175 or request a free inspection.
What Homeowner’s Insurance Covers After Hail in Arlington
Most standard Texas homeowner’s (HO-3) policies cover sudden, accidental damage from hail and windstorms ? which is exactly what a North Texas hailstorm delivers. In practical terms, a covered hail claim on your roof can include:
- Roof repair or full replacement when hail or wind damage is documented and tied to a covered storm event
- Related exterior damage ? dented gutters and downspouts, cracked or dinged siding, damaged window screens and wraps, and sometimes fencing, depending on your policy
- Interior damage caused by a resulting leak, such as stained drywall or damaged insulation (subject to your policy terms)
- Emergency mitigation ? the tarping and temporary repairs you’re often required to perform to prevent further damage. Keep those receipts; see our emergency roof repair guide for how that works.
What’s typically not covered:
- Wear, age, and neglect. Insurance covers sudden storm damage, not a roof that simply wore out. This is why documenting a specific storm date matters so much.
- Pre-existing damage that wasn’t repaired after an earlier storm.
- Cosmetic-only damage under some policies that carry a cosmetic-damage exclusion (common on metal roofs) ? read your declarations page.
Understanding Your Texas Wind/Hail Deductible
Here’s where a lot of Arlington homeowners get surprised. Most North Texas policies don’t use a flat dollar deductible for wind and hail ? they use a percentage-based deductible, typically 1?2% of your home’s insured value (Coverage A), not the market value.
A quick example: if your home is insured for $350,000 and you have a 2% wind/hail deductible, you’re responsible for the first $7,000 of a covered claim. At 1%, it’s $3,500. That number matters because it drives the core decision: is the damage extensive enough that filing makes sense?
- If a documented replacement is a $22,000 job and your deductible is $7,000, filing clearly makes sense.
- If the repair is minor and close to your deductible, it may be smarter to pay out of pocket and preserve your claims history.
Our guides on whether a 2% deductible claim is worth filing and using ACV amounts to manage your deductible walk through the math. Whatever you do, never work with a contractor who offers to “waive” or “eat” your deductible ? that’s insurance fraud in Texas, and it puts you at legal risk. A reputable roofer bills the deductible as your responsibility, plain and simple.
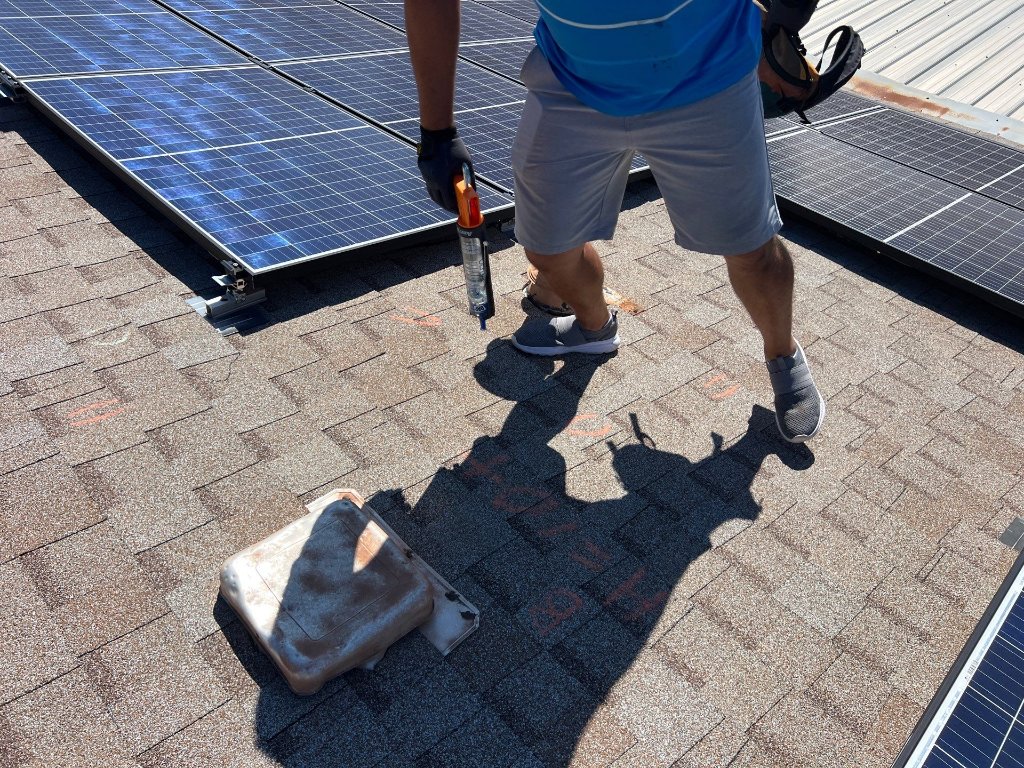 Thorough photo documentation of an Arlington roof supports an accurate claim and reduces the chance of an underpayment. (Image from the brexteriors.com gallery.)
ACV vs. RCV: How You Actually Get Paid
Two acronyms decide how much money lands in your account and when:
- RCV (Replacement Cost Value) ? what it costs to replace your roof with new materials today, with no deduction for age.
- ACV (Actual Cash Value) ? RCV minus depreciation for the age and condition of your roof.
If you have a replacement cost policy (most common), the process usually works like this:
- The insurer issues a first check for the ACV amount (RCV minus depreciation) minus your deductible.
- Once the work is completed and invoiced, they release the recoverable depreciation ? the difference between ACV and full RCV ? so you end up with the full replacement cost, minus only your deductible.
If you have an ACV-only policy (common on older roofs), you only get the depreciated value, and you cover the rest. Knowing which you have before you file prevents nasty surprises. Our overview of using ACV amounts in Texas explains how depreciation is calculated and recovered.
The Texas Filing Window and Why Timing Matters
Texas law generally gives homeowners about a two-year window to file a property insurance claim after storm damage. That’s more generous than many states ? but longer is not always better:
- The storm link fades. The longer you wait, the easier it is for an insurer to argue your damage is old wear, not a covered storm event.
- Damage compounds. A bruised, cracked roof leaks in the next storm. What was a clean hail claim becomes a tangle of “which storm caused what,” and interior damage from delay may be excluded.
- Neighborhood documentation helps. Filing while your whole street is filing, with dated storm records like our April 2026 DFW hail storm recap and Fort Worth-area hail storm history, strengthens causation.
Bottom line: you have time, but the clean, well-supported claims are the ones filed promptly after a documented storm.
How to File an Arlington Roof Claim, Step by Step
- Get a professional inspection first. Walk into the claim with photos and a written assessment, not a hunch. Becker provides free Arlington inspections and documents damage the way adjusters need to see it.
- Document from the ground yourself, too. Dented gutters and AC fins, granules in the downspouts, and any interior stains. Our how to spot hail damage guide shows what to look for.
- Call your insurer to open the claim. Give them the storm date and your documentation. They’ll assign an adjuster.
- Have your roofer meet the adjuster on-site. This is the single best way to make sure damage isn’t overlooked or undercounted. Understanding the types of adjusters in Texas helps you know who’s evaluating your roof.
- Review the scope and estimate carefully. Compare the adjuster’s line items against your roofer’s assessment. Missing items ? like flashing, drip edge, or code-required upgrades ? are common and can be supplemented.
- Complete the work and recover depreciation. Once the job is done and invoiced, submit for the recoverable depreciation to get your full RCV, minus deductible.
Why Claims Get Denied or Underpaid
Even legitimate Arlington claims hit snags. The most common reasons, and how to avoid them:
- “Damage is wear and tear, not storm.” Solved with dated storm records and a thorough professional inspection.
- Insufficient documentation. A rushed or ground-only look misses bruising and flashing damage. A photo-documented on-roof inspection fixes this.
- Undercounted scope. Adjusters sometimes miss line items; a knowledgeable roofer can supplement the claim with what’s missing.
- Missed deadlines or gaps in the paper trail. File promptly and keep every receipt and photo.
For the full breakdown, read our guides on the most common reasons roof claims get denied in North Texas and how to navigate insurance denials. If your claim was underpaid, you have options ? including supplements and, in some cases, appraisal.
Why Arlington Homeowners Work With Becker on Claims
- Free, photo-documented inspections across Arlington and Tarrant County ? evidence you keep, whether or not you file
- We meet your adjuster on-site so nothing gets missed or undercounted
- Owens Corning Preferred Contractor installing the Total Protection Roofing System, with Class 4 impact-resistant Duration Storm shingle options that can lower your future premium
- Straight talk on your deductible ? we bill it as your responsibility, never “waive” it, and help you decide whether filing makes sense
- Whole-exterior claims ? roofing, gutters, siding, windows, and fencing documented together
- Local, licensed, and here to stay ? North Richland Hills-based, founded 2018, Texas license #03-0235
See related local work in our guides for Northeast Tarrant hail insurance claims and Fort Worth hail insurance claims, browse our project gallery, and read verified homeowner feedback on our reviews page. Here’s what a recent DFW homeowner said about the claims process:
“Becker Roofing has done two roof replacements in Arlington, Texas for me. They were knowledgeable, professional, and fast. They coordinated with the insurance so I didn’t have to. They did what they said they would do and I couldn’t be happier.”
— Marty from Texas, verified Google review
Filing a roof claim in Arlington? Call 817-898-7175 or request a free inspection. You can also reach us through our contact page or see everywhere we serve on our service areas page. Becker helps you understand and document your claim; we are roofers, not licensed public adjusters or attorneys, so we don’t negotiate your settlement for you.
Frequently Asked Questions
Does homeowner’s insurance cover roof replacement after hail in Arlington?
Usually, yes ? if the hail or wind damage is documented and tied to a covered storm, a standard Texas HO-3 policy covers repair or replacement, subject to your deductible. Coverage hinges on proving the damage is storm-related rather than age or wear, which is why a thorough, dated professional inspection matters.
How much is my deductible on an Arlington roof claim?
Most North Texas policies use a percentage-based wind/hail deductible ? commonly 1?2% of your home’s insured value, not a flat dollar amount. On a home insured for $350,000, a 2% deductible means you’re responsible for the first $7,000 of a covered claim. Check your policy’s declarations page for your exact percentage.
What’s the difference between ACV and RCV on my claim?
RCV (Replacement Cost Value) is the full cost to replace your roof with new materials today. ACV (Actual Cash Value) is that amount minus depreciation for age and wear. With a replacement cost policy, you’re typically paid ACV first, then the recoverable depreciation after the work is completed ? ending up with full RCV minus your deductible.
How long do I have to file a roof insurance claim in Texas?
Texas generally allows about a two-year window to file a property insurance claim after storm damage. That said, filing promptly makes the claim much cleaner, because it’s easier to tie the damage to a specific documented storm and prevents further interior damage from a delayed repair.
Does Becker Roofing and Exteriors help with roof insurance claims in Arlington?
Yes. Becker provides free, photo-documented inspections, meets your adjuster on-site so damage isn’t missed, and helps you understand the claims process from filing through recovering depreciation. We bill your deductible honestly and never offer to waive it. Call 817-898-7175 to get started.
Written by the team at Becker Roofing and Exteriors ? a locally owned, Owens Corning Preferred Contractor based in North Richland Hills, TX, serving Arlington and the greater Dallas?Fort Worth metroplex since 2018. Call 817-898-7175 or email admin@brexteriors.com. This article is general information, not legal or insurance advice.
Roof Insurance Claim Help for Arlington, Fort Worth, and Northeast Tarrant County
After hail or wind damage, homeowners often search for a Fort Worth roofing company, a Keller roofer, or roofers Fort Worth can trust because they need clear documentation before the claim moves forward. Becker Roofing & Exteriors inspects storm damage in Arlington, Fort Worth, North Fort Worth, Keller, Lake Worth, Saginaw, Eagle Mountain, and Northeast Tarrant County.
Our inspection looks for hail bruising, lifted shingles, torn ridge caps, damaged flashing, soft-metal impact marks, attic staining, and leak paths that may support a repair or replacement scope. We explain what we find in plain language so you can make a better decision before contacting insurance, approving repairs, or waiting through another storm.
Free Roof Inspection Before or During a Claim
If you need Northeast Tarrant County storm damage roofing, roofing Keller Texas, North Fort Worth roof leak repair, or emergency help after hail, call Becker Roofing & Exteriors at 817-898-7175 for a free roof inspection.
Claim Support for Fort Worth, Lake Worth, and Northeast Tarrant Storm Damage
For homeowners searching Northeast Tarrant County storm damage roofing, roof repair Fort Worth, or roofing repair Fort Worth, the claim process is easier when the roof is documented before temporary repairs hide the evidence. Becker Roofing & Exteriors checks hail impact, wind-lifted shingles, active leaks, flashing damage, and soft-metal marks across Arlington, Fort Worth, North Fort Worth, Lake Worth, Saginaw, Eagle Mountain, Keller, and Northeast Tarrant County.
Call 817-898-7175 for a free inspection before or during the insurance claim process.
Free Inspection Before a Keller or Northeast Tarrant Claim
If you are searching for a Keller roofer, roofing Keller Texas, or a Northeast Tarrant County free roof inspection after hail, Becker Roofing & Exteriors can document the roof before a claim decision is made. We check shingles, flashing, ridge caps, vents, gutters, soft metals, attic staining, and leak paths so homeowners have clearer information.
For insurance-claim inspection help, call 817-898-7175.
Related Becker Roofing Video
Watch: What a Public Adjuster Does for Roof Insurance Claims


